Finding the RIGHT fit for Obamacare Plans in Missouri
Choosing the right Obamacare plan in Missouri depends on more than simply finding the lowest monthly premium. The right health insurance plan should balance affordability, provider access, coverage benefits, and anticipated healthcare needs.
Because every household has different healthcare priorities, there is no single ACA plan that is best for everyone. A plan that works well for a healthy individual with minimal healthcare needs may not be the right fit for a family with ongoing medical expenses or prescription medication requirements.
This guide explains how to evaluate ACA plans in Missouri and what factors to consider when determining which coverage option may be the correct fit for your situation.
What Makes an Obamacare Plan
"The Right Fit"?
The best option for a health insurance plan is typically the one that provides the right combination of coverage, provider access, and affordability for your specific needs. When comparing ACA Marketplace plans, consider factors such as:
- Provider Networks
- Prescription Drug Coverage
- Eligibility for Financial Assistance
- Cost Share Eligibility or Not
- Maximum Out-of-Pockets
- Deductibles
- Copayments
- Coinsurance
- H S A compatible or not
- Monthly Premiums
Many consumers initially focus on monthly premiums alone. However, evaluating the total cost of coverage can provide a more accurate picture of what you may spend throughout the year. The lowest premium doesn’t always mean the less you will spend.
For a complete overview of ACA coverage options available throughout the state, visit our Obamacare & ACA Health Insurance in Missouri page.
The Right Fit Obamacare Plans for Lower Monthly Premiums
Many consumers prioritize keeping monthly healthcare costs as low as possible. In these situations, Bronze plans often provide the lowest monthly premiums available through the Marketplace.
Bronze plans may be a good fit for individuals who:
- Rarely visit the doctor
- Have few ongoing medical needs
- Want protection against major medical expenses
- Prefer lower monthly insurance costs
- Looking for HSA compatibility
While Bronze plans typically have lower premiums, they often require higher out-of-pocket spending when healthcare services are used. Reviewing deductibles and maximum out-of-pocket limits is important before selecting coverage.
The Right Fit Obamacare Plans for Frequent Healthcare Usage
Individuals who regularly visit physicians, see specialists, or manage ongoing medical conditions may benefit from plans that provide lower out-of-pocket costs when care is needed.
Gold plans are often considered by consumers who:
- Visit doctors frequently
- Require ongoing treatment
- Take multiple prescription medications
- Expect higher healthcare utilization throughout the year
Although Gold plans generally have higher monthly premiums, lower deductibles and cost-sharing requirements may result in lower overall healthcare expenses for some consumers. With that said, depending on the kind of things happening to the individuals Bronze could be better. That is why consulting with someone who looks at the whole picture is very important.
The Right Fit Obamacare Plans for Families
Families have a tendency to believe they have different healthcare priorities than individual consumers. And at times things like access to pediatric care, prescription coverage, preventive services, and provider networks may all play an important role when evaluating their coverage options.
In our experience many Missouri families compare plans based on:
- Pediatric Provider Access
- Prescription Drug Coverage
- Specialist Availability
- Family deductibles
- Out-of-Pocket Maximums
- Monthly premium affordability
If the family is benefiting from the additional financial assistance and cost share savings then Silver plans are frequently chosen because they can provide a great balance between cost and coverage. But when the costs are high the evaluation becomes that much more important.
The Right Fit Obamacare Plans for
Self-Employed Individuals
Many self-employed professionals, freelancers, independent contractors, and small business owners rely on ACA Marketplace coverage for their health insurance needs.
When evaluating plans, self-employed individuals often focus on:
- Monthly premium affordability
- Access to preferred providers
- Prescription medication coverage
- Understanding their Eligibility for premium tax credits
- Overall healthcare costs
- Other alternatives when it does not work out
Depending on income and household size, self-employed individuals have a lot to compare. They are looking at how to maximize the budget not only for business but for the healthcare as well. Silver plans could help balance affordability and coverage. But on the other side of the coin a bronze plan can make them eligible for an H S A plan and put them in a lower monthly premium with additional tax advantages. Again, this is not always the case but needs to be vetting through your research.
Factors to Compare Before
Choosing a Plan
Because healthcare needs vary significantly from one person to another, comparing multiple plan features can help you identify the best overall value. Important factors to review include:
- Provider Networks – Not all plans include the same doctors, specialists, hospitals, and healthcare facilities. Before enrolling, verify that your preferred providers participate in the plan’s network. Also talk about the what if’s so that once the plan is in place you are comfortable with it til next open enrollment.
- Prescription Drug Coverage – If you need prescription medications, you should check the tier level to ensure the plan you’re considering covers those and at what benefit level, will it be deductible, copay or both. This is a huge decision in whether Bronze, Silver or Gold is the right fit.
- Total Healthcare Costs – Looking beyond monthly premiums can help provide a more accurate understanding of overall healthcare expenses. When comparing plans, review:
- Monthly premiums
- Deductibles
- Copayments
- Coinsurance
- Maximum out-of-pocket limits
- Financial Assistance Eligibility – Many Missouri residents qualify for premium tax credits and other forms of financial assistance through the Marketplace. These subsidies can significantly reduce healthcare costs and may affect which plan provides the best overall value. To learn more about available financial assistance programs, visit our Missouri ACA Subsidies page.
How to Evaluate Coverage Levels when looking for the Right Fit
Rather than focusing solely on whether a plan is Bronze, Silver, or Gold, it’s often more helpful to consider how you expect to use your health insurance throughout the year. When comparing plans, ask yourself:
- How often do you typically visit doctors or specialists?
- Do you take ongoing prescription medications?
- Do you anticipate any major medical procedures or treatments?
- Would you prefer lower monthly premiums or lower costs when receiving care?
- Are your preferred doctors and hospitals included in the plan’s network?
- Are there things in the past that you could see needing again in the future?
Different coverage levels are designed to balance monthly premiums and out-of-pocket expenses in different ways. Plans with lower premiums may require you to pay more when you receive care, while plans with higher premiums may offer lower deductibles, copayments, and coinsurance.
Reviewing your expected healthcare needs, budget, and eligibility for financial assistance can help you identify the coverage option that provides the best overall value.
Frequently Asked Questions
There is no best plan, it depends on your healthcare needs, budget, provider preferences, prescription medication requirements, and eligibility for financial assistance. There is no single ACA plan that is best for every individual or family. There is however the Right Fit and that’s what you focus on.
For some consumers, yes. Bronze plans may be a good option for individuals who want lower monthly premiums, do not expect to use healthcare services frequently and are interested in the plan being H S A compatible. However, they typically have higher deductibles and out-of-pocket costs when care is needed.
Not necessarily. Silver plans generally provide a balance between monthly premiums and healthcare expenses. For eligible applicants, Silver plans may also provide additional cost-sharing assistance that can increase their overall value.
Consider factors such as expected healthcare usage, preferred doctors and hospitals, prescription medication needs, monthly budget, and subsidy eligibility. Comparing multiple plans can help identify the best fit and talking it through with someone that does it daily.
Most consumers can only change plans during the annual Open Enrollment Period, that is why working to get it as right as possible the first time is so important. Sometimes things change throughout the year, but you plan the best you can using past experiences, present situations to help predict the Right Fit for future outcomes. Certain qualifying life events may create eligibility for a Special Enrollment Period outside the normal enrollment window and those are very case by case. For more information, see our Missouri ACA Open Enrollment page.
Get Help Comparing Obamacare Plans
in Missouri
With multiple coverage levels, insurance carriers, provider networks, financial assistance opportunities available, yearly carrier changes and pricing volatility comparing ACA plans can sometimes feel overwhelming. MBhealth helps Missouri residents evaluate their options, compare available plans, understand subsidy opportunities, and select coverage that aligns with their healthcare needs and budget. We cover you as if it is our situation. Let us walk by your side during your healthcare decisions and beyond.
Contact MBhealth today to learn more about Obamacare plans in Missouri and find the coverage that’s right for you.
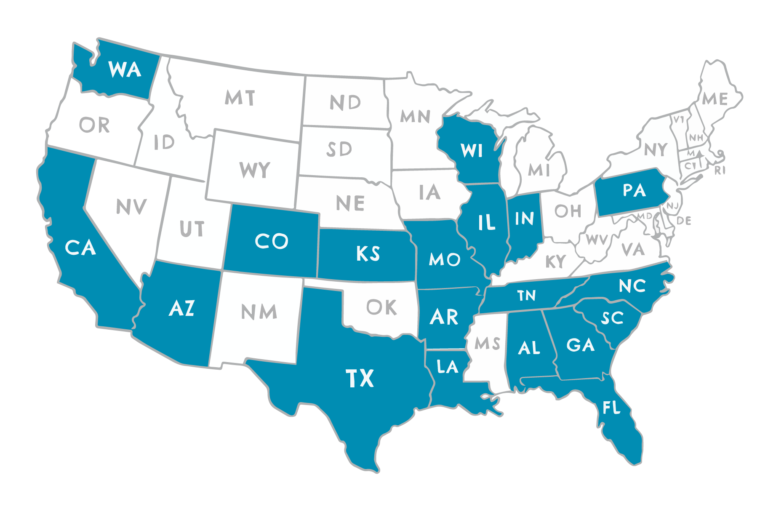
STATE LICENSURE
MBhealth is licensed in the following states:
- Alabama
- Arizona
- Arkansas
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Kansas
- Louisiana
- Missouri
- North Carolina
- Pennsylvania
- South Carolina
- Tennessee
- Texas
- Washington
- Wisconsin