Obamacare Plans in St. Louis, MO
Choosing health insurance based on the monthly premium alone can leave you with coverage that doesn’t work well when you actually need care. ACA plans available to St. Louis residents can differ in their deductibles, provider networks, prescription coverage, cost-sharing requirements, and other important details.
The right choice depends on how you expect to use your insurance as well as what you can comfortably spend on coverage throughout the year.
This guide explains Obamacare plan options in St. Louis, how Bronze, Silver, and Gold coverage levels compare, what to consider when reviewing local provider networks and healthcare costs, and how to choose coverage that fits your needs.
Available ACA Plan Options in St. Louis, MO
Health insurance plans offered through the Affordable Care Act (ACA) Marketplace must meet federal coverage requirements and provide a set of essential health benefits.
These benefits include:
- Preventive care
- Emergency services
- Hospitalization
- Prescription medications
- Mental health services
- Maternity and newborn care
- Pediatric services
Although every ACA-compliant plan includes these core benefits, that doesn’t mean every plan provides the same coverage experience. Costs, provider networks, prescription formularies, and other plan details can vary considerably.
Key Factors to Compare
When reviewing Obamacare plans in St. Louis, look at how each option works as a whole rather than comparing one number. Important factors include:
- Monthly premiums
- Annual deductibles
- Copayments
- Coinsurance
- Maximum out-of-pocket costs
- Provider networks
- Prescription drug coverage
Your healthcare needs matter, too. A plan that works well for someone who rarely visits a doctor may be less suitable for someone who regularly sees specialists, takes multiple prescriptions, or expects ongoing treatment.
For a broader overview of ACA health insurance options available locally, visit our Obamacare & ACA Health Insurance in St. Louis page.
Comparing Coverage Levels of ACA Plans
ACA Marketplace plans are generally organized into metal tiers. Bronze, Silver, and Gold plans all cover essential health benefits, but they differ in how the cost of healthcare is divided between you and the insurance company.
Understanding that tradeoff can help you decide whether you would rather pay less each month and potentially more when you need care or pay a higher premium in exchange for lower out-of-pocket expenses.
Bronze plans typically offer some of the lowest monthly premiums among ACA coverage levels. In exchange, deductibles and other out-of-pocket costs tend to be higher when you receive healthcare services.
This structure may work for people who don’t expect to use their insurance frequently and want to keep monthly expenses down. However, it’s important to consider what you could afford to pay if you experience an unexpected illness, injury, or other significant medical need.
Silver plans generally provide a more even balance between monthly premiums and out-of-pocket healthcare expenses. They can be a practical choice for people who expect moderate healthcare usage and want to avoid either extreme in their cost-sharing.
Silver coverage also has an important distinction for eligible Marketplace consumers: cost-sharing reductions that can lower deductibles, copayments, and coinsurance are generally available only through qualifying Silver plans.
Gold plans generally require higher monthly premiums while shifting more of the cost of covered healthcare services to the insurance company.
They may provide better overall value for people who regularly visit doctors or specialists, require ongoing medical treatment, take recurring prescription medications, or otherwise expect to use their insurance frequently.
When comparing a Gold plan with a lower-premium option, consider your likely healthcare expenses across the entire year rather than looking only at what you’ll pay each month.
Local Provider Networks in St. Louis, MO
St. Louis offers access to a wide range of doctors, hospitals, specialists, and other healthcare facilities, but individual ACA plans don’t necessarily provide in-network access to all of them.
Each plan has a provider network that determines where you can generally receive covered services at negotiated in-network rates. Depending on the plan, receiving non-emergency care outside that network may result in higher costs or little to no coverage.
When comparing St. Louis Obamacare plans, consider:
- Your current primary care physician
- Specialists you see regularly
- Preferred hospitals and healthcare systems
- Nearby urgent care facilities
- Other healthcare providers you rely on
- Pharmacies and prescription coverage
If continuing care with a particular provider is important to you, confirm that the provider participates in the specific plan you’re considering. An insurance carrier may offer multiple plans with different networks, so knowing that a doctor accepts the insurance company generally isn’t always enough.
Common Marketplace Insurance Networks in St. Louis
Multiple insurance companies may offer ACA Marketplace coverage to St. Louis residents. Carrier participation and individual plan availability can change based on location and plan year.
Marketplace insurers serving Missouri may include:
- Anthem Blue Cross and Blue Shield
- Ambetter (Home State Health)
- UnitedHealthcare
- Medica
- Oscar Health
Different carriers may offer different provider networks, premiums, deductibles, prescription formularies, and plan designs. Comparing those details can help you determine which available coverage gives you appropriate access to the healthcare services you use.
Monthly Costs and Out-of-Pocket Expenses for ACA Coverage
Your monthly premium is only one part of what health insurance may cost you. To get a clearer picture of a plan’s potential financial impact, consider both the amount you’ll pay to maintain coverage and the expenses you could face when you use it.
These costs may include:
- Monthly premiums
- Deductibles
- Copayments
- Coinsurance
- Maximum out-of-pocket limits
For example, a plan with a relatively low premium may require you to meet a larger deductible before the insurance company begins paying its share of certain covered services. A plan with a higher premium may cost more each month but reduce what you pay when you receive care.
Eligible St. Louis residents may also qualify for premium tax credits or other financial assistance through the Health Insurance Marketplace. These savings can change the actual cost of the plans available to you. To learn more about Marketplace enrollment and subsidy opportunities, visit our St. Louis Health Insurance Marketplace page.
Choosing the Best ACA Plan for Your Needs
There isn’t one Obamacare plan that’s best for every St. Louis resident. Choosing the right coverage requires looking at your own healthcare needs and financial priorities. Before enrolling, consider:
- How frequently you expect to use healthcare
- Any ongoing medical conditions or treatments
- Prescription medications you take
- Doctors, specialists, and hospitals you want to use
- Healthcare needs for other family members on the plan
- What you can afford in monthly premiums
- What you could afford in unexpected out-of-pocket costs
- Whether you qualify for financial assistance
It’s also helpful to think about your total potential healthcare spending rather than automatically choosing the plan with the cheapest premium. If you expect significant healthcare use, paying more each month for coverage with lower cost-sharing may ultimately make more financial sense.
Comparing several available options can help you find coverage that balances affordability, provider access, and protection against healthcare expenses.
For a broader overview of ACA coverage and resources available throughout the state, visit our Obamacare & ACA Health Insurance in Missouri page.
Frequently Asked Questions
Coverage tiers mainly differ in the way costs are divided between you and your health insurance plan. Bronze plans often feature lower monthly premiums but require you to pay more when you receive care. Gold plans generally have higher monthly costs in exchange for lower out-of-pocket expenses for covered services. Silver plans fall in the middle, offering a combination of moderate premiums and cost-sharing that works well for many individuals and families.
That depends on the provider network for the specific plan you choose. If you want to continue seeing a particular doctor, specialist, or using a preferred hospital, verify that they participate in the plan’s network before enrolling.
The cost of coverage varies based on factors such as your age, location, household circumstances, selected plan, and eligibility for financial assistance. Premium tax credits may reduce monthly costs for eligible Marketplace consumers.
No. ACA-compliant plans must meet certain coverage requirements, but individual plans can differ in premiums, deductibles, provider networks, prescription drug coverage, copayments, coinsurance, and other details.
The right plan depends on your healthcare needs, budget, preferred doctors and hospitals, prescription medications, expected healthcare usage, and eligibility for financial assistance.
Compare both monthly premiums and potential out-of-pocket expenses, and make sure the providers and medications that matter to you are covered. Looking at the complete cost and coverage of several plans can help you find the option that best fits your situation.
Get Help Comparing Obamacare Plans in St. Louis
Sorting through premiums, deductibles, provider networks, prescriptions, and coverage levels can make choosing an ACA plan complicated. MBhealth helps St. Louis residents compare available options and understand how each plan may work with their healthcare needs and finances.
We’ll help you look beyond the monthly premium to evaluate the costs, benefits, provider access, and financial assistance that may affect your decision.
Contact MBhealth today to compare Obamacare plans in St. Louis, MO, and find coverage that works for you.
STATE LICENSURE
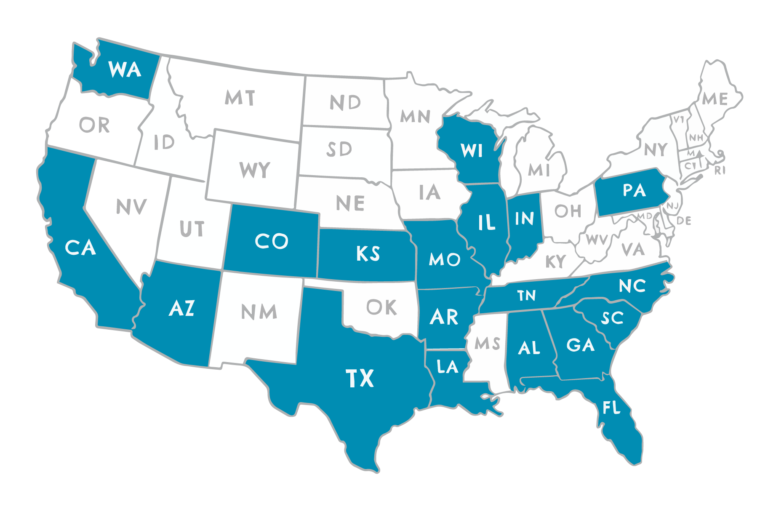
MBhealth is licensed in the following states:
- Alabama
- Arizona
- Arkansas
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Kansas
- Louisiana
- Missouri
- North Carolina
- Pennsylvania
- South Carolina
- Tennessee
- Texas
- Washington
- Wisconsin