Obamacare & ACA Health Insurance in Tennessee
Health insurance plays an important role in protecting both your health and your finances. However, with different plan types, provider networks, premiums, deductibles, and financial assistance programs to evaluate, choosing coverage can sometimes feel complicated.
The Affordable Care Act (ACA), often referred to as Obamacare, expanded access to health insurance by creating the Health Insurance Marketplace and establishing important consumer protections. Today, many Tennessee residents use ACA coverage to obtain comprehensive health insurance that fits their healthcare needs and budget.
This guide explains ACA coverage in Tennessee, eligibility requirements, available plan options, financial assistance opportunities, enrollment periods, and how MBhealth can help you compare coverage.
Overview of ACA Health Insurance in Tennessee
The Affordable Care Act created a system that allows individuals and families to compare health insurance plans that meet federal coverage standards. These plans are designed to provide comprehensive healthcare coverage while offering options for a wide range of budgets and healthcare needs.
ACA-compliant plans generally include coverage for essential health benefits such as:
Tennessee residents can compare available plans through the Health Insurance Marketplace and may qualify for financial assistance that helps reduce the overall cost of coverage. To learn more about how Marketplace coverage works, visit our Tennessee Health Insurance Marketplace page.
- Preventive care
- Emergency services
- Hospitalization
- Prescription medications
- Maternity and newborn care
- Mental health services
- Pediatric services
Who Qualifies for ACA Coverage in Tennessee?
Many Tennessee residents are eligible to enroll in ACA Marketplace coverage. In most situations, you may qualify if you:
- Live in Tennessee
- Are a U.S. citizen or lawfully present immigrant
- Are not currently incarcerated
- Do not have access to certain affordable employer-sponsored coverage
One of the most important protections provided by the ACA is that insurance companies cannot deny coverage because of a pre-existing medical condition. These protections apply regardless of your health history or current healthcare needs.
Does Your Employment Situation Impact Your ACA Eligibility?
ACA Marketplace coverage is available to individuals in many different employment situations. You may be eligible to enroll if you are:
- Self-employed
- Between jobs
- Working part-time
- Retired before becoming eligible for Medicare
- Running a small business
- Not offered health insurance through an employer
- Offered employer coverage that does not meet affordability requirements
ACA Plan Options in Tennessee
ACA Marketplace plans are available in several coverage levels, allowing consumers to choose a plan that aligns with their healthcare needs and financial goals. Although all ACA-compliant plans include the same essential health benefits, plans differ in how healthcare expenses are shared between the insurance company and the policyholder.
Some plans prioritize lower monthly premiums, while others provide lower costs when healthcare services are used. Understanding these differences can help you choose coverage that provides the best overall value for your situation.
For a more detailed comparison of available coverage options, visit our Tennessee Obamacare Plans page.
Bronze Plans
Bronze plans generally feature lower monthly premiums but higher out-of-pocket expenses when healthcare services are needed. These plans are often selected by individuals who:
- Want lower monthly insurance costs
- Do not expect frequent medical care
- Are generally healthy
- Want protection from major healthcare expenses
For many consumers, Bronze plans offer an affordable way to maintain health insurance while protecting against unexpected medical costs.
Silver Plans
Silver plans balance monthly premiums with healthcare expenses and remain one of the most popular Marketplace options.
Many families and individuals choose Silver plans because they offer a practical combination of affordability and coverage. Eligible applicants may also qualify for additional cost-sharing assistance that helps lower deductibles, copayments, and other healthcare expenses.
Gold Plans
Gold plans typically have higher monthly premiums but lower costs when healthcare services are used. They may be particularly attractive for people who:
- Visit healthcare providers regularly
- Manage ongoing health conditions
- Take prescription medications
- Expect higher healthcare utilization
Although monthly costs are often higher, many consumers appreciate the reduced out-of-pocket expenses when receiving care.
Choosing the Right Coverage
Finding the right health insurance plan involves more than simply comparing monthly premiums. The plan with the lowest monthly cost is not always the most affordable option once deductibles, copayments, and other healthcare expenses are considered.
When evaluating ACA plans, it is helpful to consider factors such as:
- Household budget
- Expected medical needs
- Preferred doctors and hospitals
- Prescription medications
- Eligibility for subsidies
It is also important to review provider networks and covered medications before enrolling. Confirming that your preferred healthcare providers participate in a plan’s network can help prevent unexpected expenses and disruptions in care.
ACA Subsidies and Tax Credits in Tennessee
One of the most valuable benefits of Marketplace coverage is access to financial assistance programs designed to make health insurance more affordable.
Many Tennessee residents qualify for premium tax credits that help lower monthly health insurance premiums. Depending on household income and family size, these savings can substantially reduce the overall cost of coverage.
Learn more about financial assistance on our Tennessee ACA Subsidies page.
What Can ACA Subsidies Help Pay For?
Many consumers are surprised to discover they qualify for savings through the Marketplace.
Depending on eligibility, financial assistance may help reduce:
- Monthly premiums
- Deductibles
- Copayments
- Coinsurance expenses
These programs help make comprehensive healthcare coverage more accessible for many individuals and families throughout Tennessee.
What Determines Subsidy Eligibility?
The amount of financial assistance available varies from one household to another. Common factors that may affect eligibility include:
- Household income
- Family size
- Age
- Location
- Plan selection
Because eligibility can change when household circumstances change, reviewing your options each year can help ensure you receive any available assistance.
Open Enrollment Information for Tennessee Residents
Most individuals enroll in ACA coverage during the annual Open Enrollment Period. Open Enrollment is the primary time each year when eligible consumers can enroll in coverage, switch plans, update existing coverage, and review financial assistance opportunities.
During Open Enrollment, Tennessee residents may:
- Enroll in a new plan
- Change plans
- Update coverage
- Review subsidy eligibility
Although specific enrollment dates can vary, Open Enrollment generally occurs during the fall and winter months. Visit our Tennessee ACA Enrollment Page for more information.
Even if you currently have Marketplace coverage, reviewing available plans annually can be beneficial. Premiums, provider networks, covered medications, and subsidy eligibility can all change from year to year.
What If I Miss Open Enrollment?
Certain qualifying life events may create eligibility for a Special Enrollment Period outside the annual Open Enrollment window.
Common qualifying events include:
- Marriage
- Divorce
- Birth or adoption of a child
- Loss of employer coverage
- Moving to a new coverage area
- Changes in household income
If you experience a qualifying life event, you may be eligible to enroll in coverage or make plan changes outside the standard enrollment period.
Major Cities We Serve in Tennessee
MBhealth helps individuals and families throughout Tennessee explore ACA health insurance options and compare available Marketplace coverage.
We assist residents in communities across the state, including:
- Nashville, TN
- Memphis, TN
- Knoxville, TN
- Chattanooga, TN
- Clarksville, TN
- Murfreesboro, TN
No matter where you live in Tennessee, our team can help you compare plans, understand healthcare costs, review subsidy opportunities, and evaluate coverage options.
Why Work with MBhealth?
Comparing health insurance plans can be time-consuming, especially when reviewing provider networks, healthcare costs, coverage levels, and financial assistance opportunities.
MBhealth helps individuals and families:
- Compare ACA Marketplace plans
- Understand subsidy eligibility
- Review provider network options
- Evaluate healthcare costs
- Navigate enrollment requirements
- Find coverage that fits their needs and budget
Our goal is to simplify the process and provide clear information so you can make confident healthcare coverage decisions.
Frequently Asked Questions
There are many options available for long-term care. First, you can obtain traditional long-term care insurance that covers the cost of many different types of care:
- At-home care where you can get skilled nursing care, rehabilitative therapy or help with personal care
- Residence in memory care facilities
- Hospice care
- Adult day service center care
- Residential living facilities
- Convalescent homes
Second, you can get a hybrid policy that combines traditional life insurance with long-term care insurance. This kind of policy gives you access to the death benefit funds provided by the life insurance policy to help you pay for long-term care.
The third choice is to add a rider to your life insurance policy that allows you to use part or all of your death benefit for your long-term care.
There are many variables to be considered when choosing these policies from the insurance companies that offer them. One of those variables is the maximum age at which the policy can be issued. Another is the length of time the costs of care will be covered. It’s important to compare all the variables of any long-term care policy you are considering. For help obtaining your best long-term care coverage, contact MBhealth.
Any of the insurance companies offering long-term care insurance require certain benefit “triggers” to be experienced before they start paying for care. For example:
- The individual is unable to manage at least two of six Activities of Daily Living (ADL) without help, such as being able to move from a chair into bed or keeping themselves clean
- They have a cognitive impairment
- A doctor recommends they begin to receive long-term care
In the case of the ADLs, the person must have lacked the ability to manage these ADLs for at least 90 days. If cognitive impairment exists, the person must require significant supervision.
Pre-existing conditions that caused these disabilities are not covered by long-term care insurance. There may also be a maximum limit on the years or amount of benefits to be paid.
Before benefits begin to be paid, there is often a waiting period which some companies call an elimination period. This typically lasts from 20 to 100 days before the policy will pay for long-term care costs.
Once a long-term care policy is obtained, the premiums and benefits may change each year to keep up with inflation. Are you looking for long-term care insurance? Talk to MBhealth to get the best care insurance for your situation.
Long-term care insurance policies often pay for care that is received at home, for example, for payment of home health care or personal care assistance. In other cases, a person may need to take up residence in a memory care or rehabilitation facility. The benefits can be paid to the family in the event of home care or the facility in the event of residential care.
Many companies that previously offered long-term care insurance have stopped doing so. There are currently six companies offering this type of insurance. If you are considering long-term care insurance and you can afford it, your prices will be lower if you obtain this insurance while you are in your 50s or 60s.
Over time, your premiums will increase if your policy has a provision for inflation growth. At the time you will need long-term care, care costs will undoubtedly be higher than they are today. To ensure that you receive the kind of care you want when you are no longer able to care for yourself, your benefits need to gradually increase along with the rate of inflation.
When you are shopping for long-term care insurance, contact MBhealth to find the perfect policy to put your mind at rest.
Benefits of long-term care insurance cover the many expenses of care provided to an older person who can no longer fully take care of themselves. The criteria for beginning to receive these benefits may include:
- Being unable to perform at least two out of six Activities of Daily Living such as feeding oneself, bathing, dressing or moving from chair to bed
- Experiencing cognitive impairment
- Receiving a recommendation from a medical doctor
When a person is qualified for long-term care, this insurance policy begins to pay for the costs for the person’s care. The exact benefits provided vary somewhat by state, but typically include:
- Nursing home care
- Residence in a care facility that provides assisted living
- Home health care
- Adult day care
- Homemaker services
- Hospice
- Respite care
Some long-term care insurance policies require a waiting period of 20 to 100 days, but others do not have any waiting period.
Many residential facilities offer personal care, recreational activities, meal service, and medical services. Aging individuals obtain long-term care insurance to ensure their comfort, protect their wealth and ensure there is an inheritance for the next generation. When you are comparing long-term care policies, contact MBhealth for guidance to the best type of policy for your situation.
The amount of long-term care you should have is a very personal decision that is best made with advice from an experienced insurance consultant. Of course, the amount of long-term care insurance you can afford is also a determinant of how much insurance you should have.
You will need to take the following factors into account when you make your choice:
- Your current age
- Your current health condition
- How long you want the care benefits to last
- Whether or not you want your benefits to keep up with increases due to inflation
Your net worth and savings also have relevance, as the more savings you have, the less insurance you may need or choose to self insure for a longer period.
You also may want to fold your long-term care insurance into your life insurance policy, creating a hybrid that enables you to utilize death benefits for your long-term care.
If you make no plans for long-term care insurance, you will probably be limited to Medicaid which provides limited choice for those who need skilled nursing care. If you are currently in the market for long-term care insurance, please call MBhealth for guidance as you decide on the best arrangements for your future.
What Our Clients Say
Contact MBhealth to Secure Long-Term Care Insurance to Protect Your Future
Long-term care insurance is a valuable financial tool for those planning for the future. By securing coverage while you are still healthy, you can protect your savings, ensure access to quality care, and alleviate the potential financial burden on your family.
If you’re planning ahead for your retirement years, then it’s time to consider this insurance. To make this task simpler and stress-free, contact MBhealth. Call (314) 816-1696 to schedule a consultation or fill in the contact form below.
STATE LICENSURE
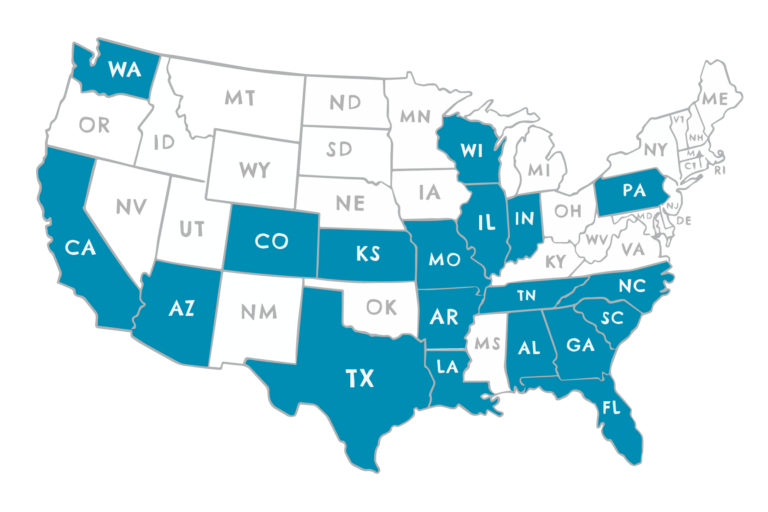
MBhealth is licensed in the following states:
- Alabama
- Arizona
- Arkansas
- California
- Colorado
- Florida
- Georgia
- Illinois
- Indiana
- Kansas
- Louisiana
- Missouri
- North Carolina
- Pennsylvania
- South Carolina
- Tennessee
- Texas
- Washington
- Wisconsin